Nov 18, 2026 · Matthew Jones
By Matthew Jones | Precious Metals Analyst, Britannia Bullion
Imagine you've worked hard, saved carefully and built up £100,000 in your bank account.
You've seen the familiar FSCS protection notice. Your savings are protected up to £120,000.
You feel reassured. And why wouldn't you?
After all, that's what a guarantee is supposed to do.
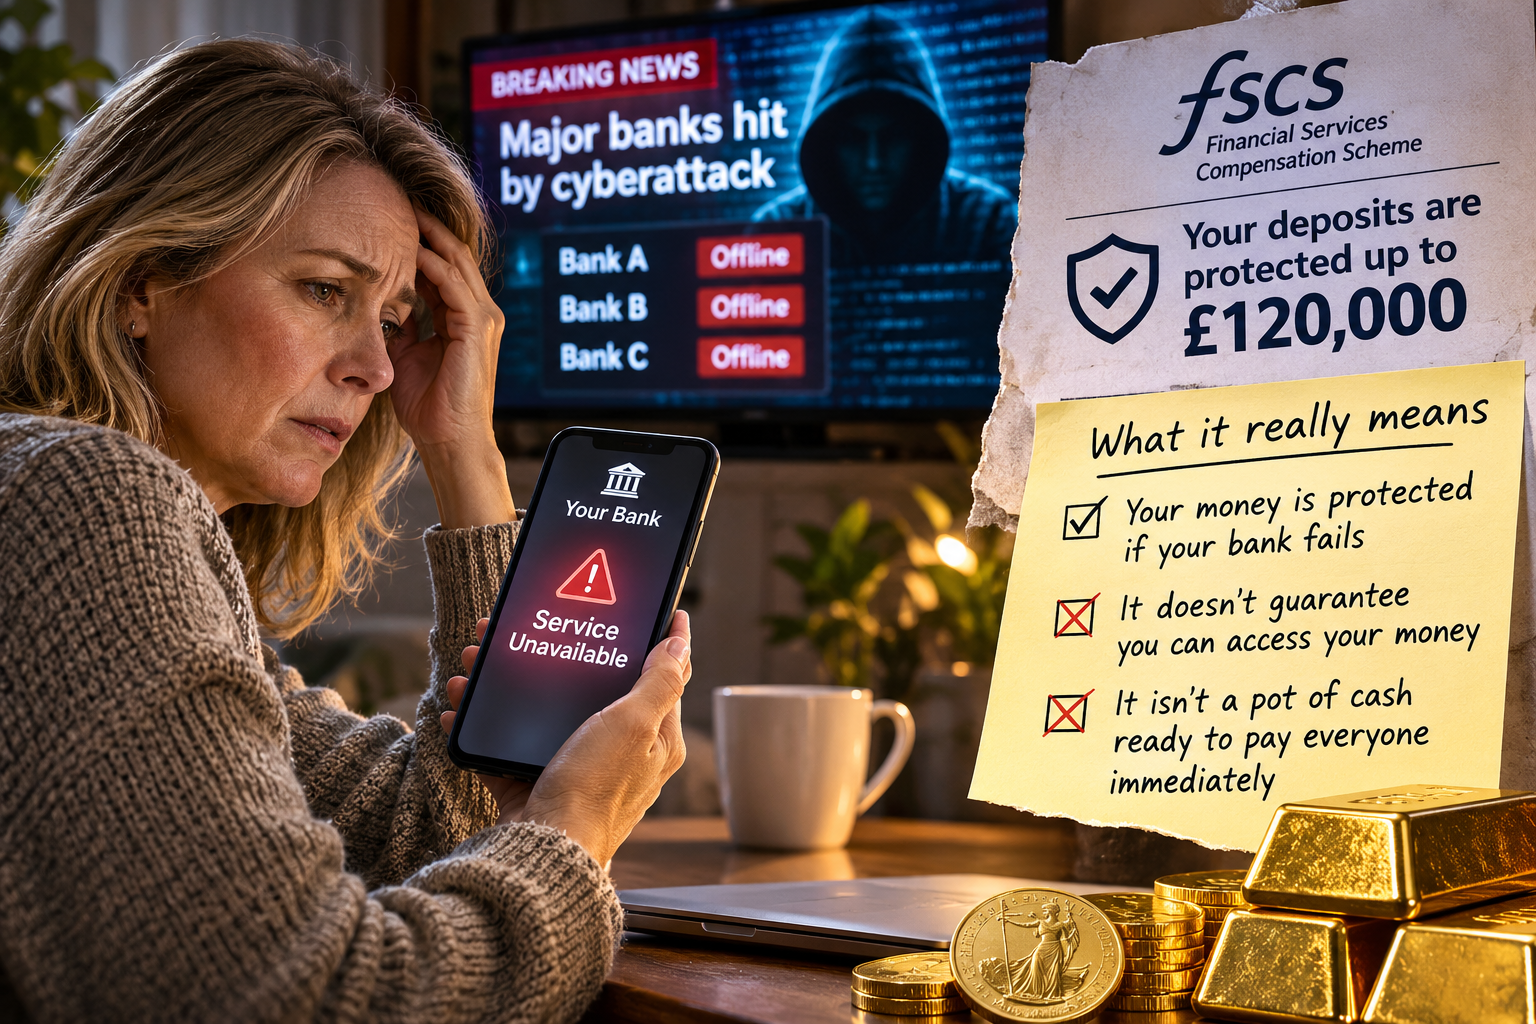
Now imagine waking up tomorrow morning to discover that your bank has suffered a major cyberattack.
You cannot log in. You cannot transfer money. Your debit card isn't working. The bank's telephone lines are overwhelmed.
You turn on the news and discover that two other major banks are experiencing similar problems.
But you're not particularly worried about losing your savings.
You're protected by the FSCS. Aren't you?
Well, here's where things become rather more complicated.
Protected Doesn't Necessarily Mean Accessible
The Financial Services Compensation Scheme (FSCS) does not guarantee that you can access your money whenever you need it.
If your bank has been hacked but remains financially viable, the FSCS may have no obligation to compensate you at all.
Not after 24 hours. Not automatically after three days. And not simply because the disruption has continued for a week.
The protection generally becomes payable when an authorised bank fails and the relevant legal conditions are met.
Your bank could be completely inaccessible to you, yet your FSCS protection might not have been triggered.
And here's something else that may surprise you.
Where Is the Money?
The FSCS does not have enough cash sitting in a giant savings account to repay every protected depositor.
Its reported cash balance at the end of March 2026 was approximately £255 million.
That's not £255 billion.
It's £255 million.
Of course, the FSCS has other ways to obtain money. It can borrow, collect levies from financial institutions and, in exceptional circumstances, seek government support.
But that means the money needed to honour a major wave of compensation claims may have to be raised when the crisis is already happening.
Now imagine several major banks failing at once.
The very institutions expected to help fund the compensation system could themselves be struggling.
None of this means the FSCS guarantee is worthless. Far from it. It provides important legal protection when a bank fails, with eligible depositors normally compensated within seven working days.
But it raises a question that deserves a much clearer answer.
How many people understand that having their money protected does not necessarily mean having their money available?
Because those are two very different things.
A Guarantee Is Not the Same as Access
In an increasingly digital world, cyberattacks are becoming more sophisticated and financial institutions depend on interconnected technology.
We are encouraged to hold our money digitally. To rely on banking apps, electronic payments and financial systems we cannot physically see or control.
Yet the protection designed to reassure us does not necessarily help when those systems stop working.
And if several major banks were to suffer simultaneous failures, the question would no longer be simply whether depositors were legally entitled to compensation.
It would also be how quickly the necessary funds could be raised and distributed during a wider financial crisis.
A promise to repay is not the same as having the money immediately available to do so.
Protection, Not Speculation
This is not an argument for abandoning banks, nor is it a prediction that Britain's financial system is about to collapse.
It is an argument for understanding the difference between owning wealth and being able to access it.
Physical gold held directly outside the banking system offers a different form of protection.
It cannot be erased by a cyberattack on a bank's computer systems. Its ownership does not depend on an online banking application functioning correctly.
Gold has its own considerations, including secure storage, price fluctuations and the practicalities of selling it. But it does not carry the same dependence on digital banking infrastructure.
For those who have spent a lifetime building their savings, perhaps the sensible question is not whether to trust the banking system.
It is whether to depend upon it entirely.
Because the greatest misunderstanding may not be about how much money the FSCS guarantees.
It's about what the word "guaranteed" actually promises.
And in a world where financial disruption can arrive without warning, understanding that difference has never been more important.
Protect. Preserve. Pass on.
About the Author
Matthew Jones is Co-Founder and Precious Metals Analyst at Britannia Bullion, specialising in physical gold, wealth preservation and the economic forces shaping precious metals markets.
A regular contributor to Kitco News, Matthew writes about inflation, monetary policy, geopolitical uncertainty and the growing challenges facing traditional financial systems.
His work focuses on helping individuals understand the risks to their wealth and the role physical gold can play in protecting purchasing power over the long term.