Oct 21, 2026 · Matthew Jones
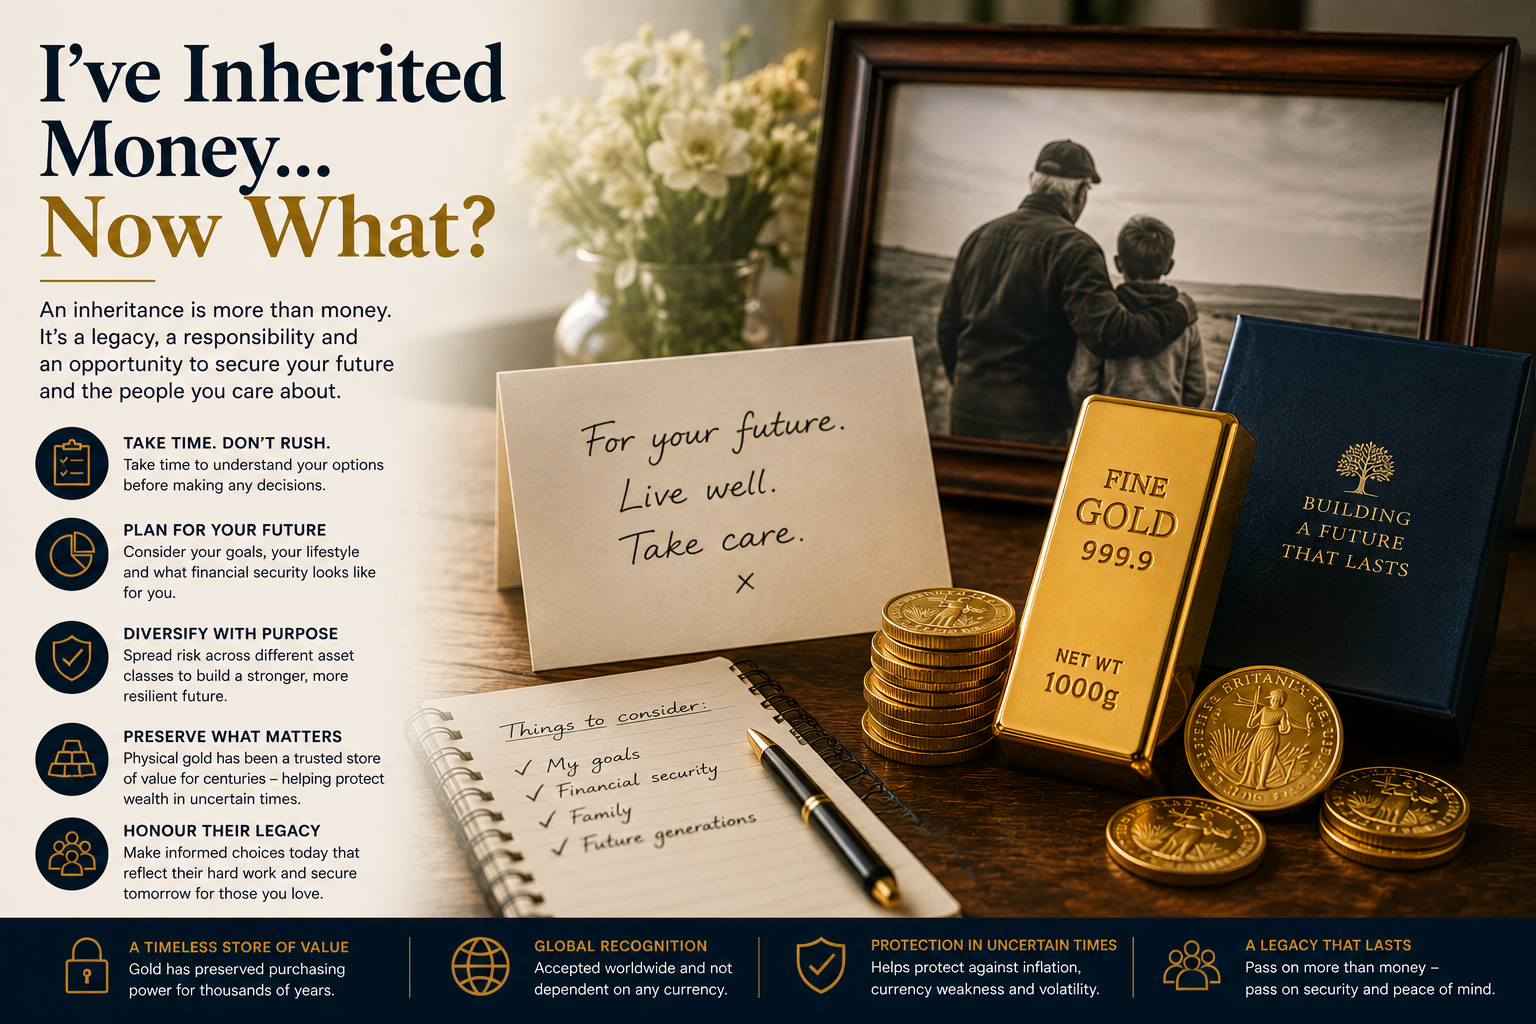
Honouring the past. Protecting the future.
Few moments in life are as emotionally complicated as receiving an inheritance.
It is rarely just about the money.
More often, it represents the life, hard work and sacrifices of someone who mattered to you. Behind the figure on a bank statement may be decades of early starts, careful saving and decisions made with the family in mind.
Alongside the practical questions comes a responsibility that many people feel deeply:
“I don’t want to waste what they spent a lifetime building.”
That is an understandable feeling. But honouring someone’s legacy does not mean you have to know immediately what to do with it.
Give yourself permission to pause
If you have recently inherited money, you do not need to rush into a major investment decision.
Grief and financial pressure are difficult companions. The arrival of a substantial sum can bring advice from every direction, leaving you feeling that you ought to be doing something before you have had time to think clearly.
Take a breath.
Understand what you have inherited, establish any outstanding legal or tax obligations, and review your own financial position.
There is a difference between giving yourself time to make a considered decision and leaving the money without a plan indefinitely.
While you are deciding, check how your cash is protected. The Financial Services Compensation Scheme currently protects eligible deposits up to £120,000 per person, per authorised firm. Qualifying inheritances may receive temporary high balance protection of up to £1.4 million for six months, subject to the scheme’s conditions. Different banking brands can share an authorisation, so check the underlying firm rather than relying on the name above the door. fscs.org.uk
That breathing space can be valuable.
Use it.
Decide what this money needs to do
For some people, an inheritance provides financial security for the first time.
For others, it might reduce a mortgage, supplement retirement income, support children or grandchildren, or create opportunities that previously felt out of reach.
Whatever the amount, the starting point should be your circumstances.
A useful first step is to ask yourself three questions:
Do I need access to this money in the near future?
What level of risk am I genuinely comfortable taking?
What would I like this inheritance to make possible—for me and for the people I care about?
The wishes and values of the person who left you the money may help guide those answers. But you do not need to feel guilty about using some of it to improve your own life.
Security has value. So does time with your family. Sometimes the most meaningful use of an inheritance is something its previous owner would have been delighted to see you enjoy.
Protecting the amount is only part of the task
Once the immediate decisions are settled, another question deserves attention:
What will this money actually buy in five, ten or twenty years?
Figures released by the Office for National Statistics on 21 October show UK consumer price inflation rose to 3.5% in September, up from 3.1% in August. Office for National Statistics
For someone receiving an inheritance, this is more than an economic headline.
Money can remain untouched in an account while its purchasing power gradually declines if the interest earned, after any tax, fails to keep pace with rising prices.
That does not make cash the wrong choice. It remains essential for emergencies, everyday spending and commitments that are approaching.
It does mean that protecting a balance and protecting what that balance can buy are two different considerations.
Someone may have spent decades accumulating that wealth. It is worth thinking carefully about how to preserve its usefulness for the decades ahead.
Where physical gold can fit
There are many ways to put an inheritance to work.
You might reduce expensive debt, consider pension contributions within the relevant rules, invest for long-term growth, strengthen your emergency reserve or help the next generation.
These choices can sit alongside one another.
Physical gold may also have a place within that broader plan, particularly where the aim is to preserve a proportion of wealth over the long term and diversify exposure to currencies and financial markets.
Gold has a long history as a store of value. Its appeal rests partly on being a tangible asset that, when owned outright, is not another institution’s promise to repay you.
Central banks continue to see a role for it too. According to the World Gold Council, central banks and other official institutions bought a net 289 tonnes in the second quarter of 2026. World Gold Council
Their circumstances differ from those of a private investor, but their continued buying illustrates gold’s enduring place in reserve diversification.
For a family, the question is how an appropriate holding might complement the cash, pensions, investments and property they already own.
Gold does not pay interest or dividends. Its sterling price can fall, sometimes sharply, and buying, selling, secure storage and insurance involve costs. It should not be treated as a guaranteed inflation hedge over every period, or as a substitute for money you may need soon.
Those considerations belong in an honest conversation about preserving wealth.
The aim is to make a considered decision about the role each asset serves.
A legacy that continues
Perhaps the greatest value of an inheritance is the opportunity it provides.
An opportunity to feel more secure.
To make choices with greater confidence.
To help your children or grandchildren.
And to ensure that the work of one generation continues to benefit the next.
You do not have to predict every market movement or find the perfect moment to act. You need a plan that reflects your needs, your timescale and the level of uncertainty you can comfortably live with. For significant sums or complicated circumstances, qualified financial and tax advice can help bring those decisions together.
An inheritance is not just money changing hands. It is responsibility changing hands.
That responsibility deserves care, but it should not become a burden.
After all, one of the greatest tributes you can pay to someone who spent a lifetime building wealth is to ensure that what they created continues to protect—and enrich the lives of—the people they cared about most.
About the author
Matthew Jones is Co-founder and Precious Metals Analyst at Britannia Bullion. He writes about gold, purchasing power and the role physical precious metals can play in long-term wealth preservation.
This article provides general information and does not constitute personal financial or tax advice. Gold prices can fall as well as rise.