Oct 21, 2026 · Matthew Jones
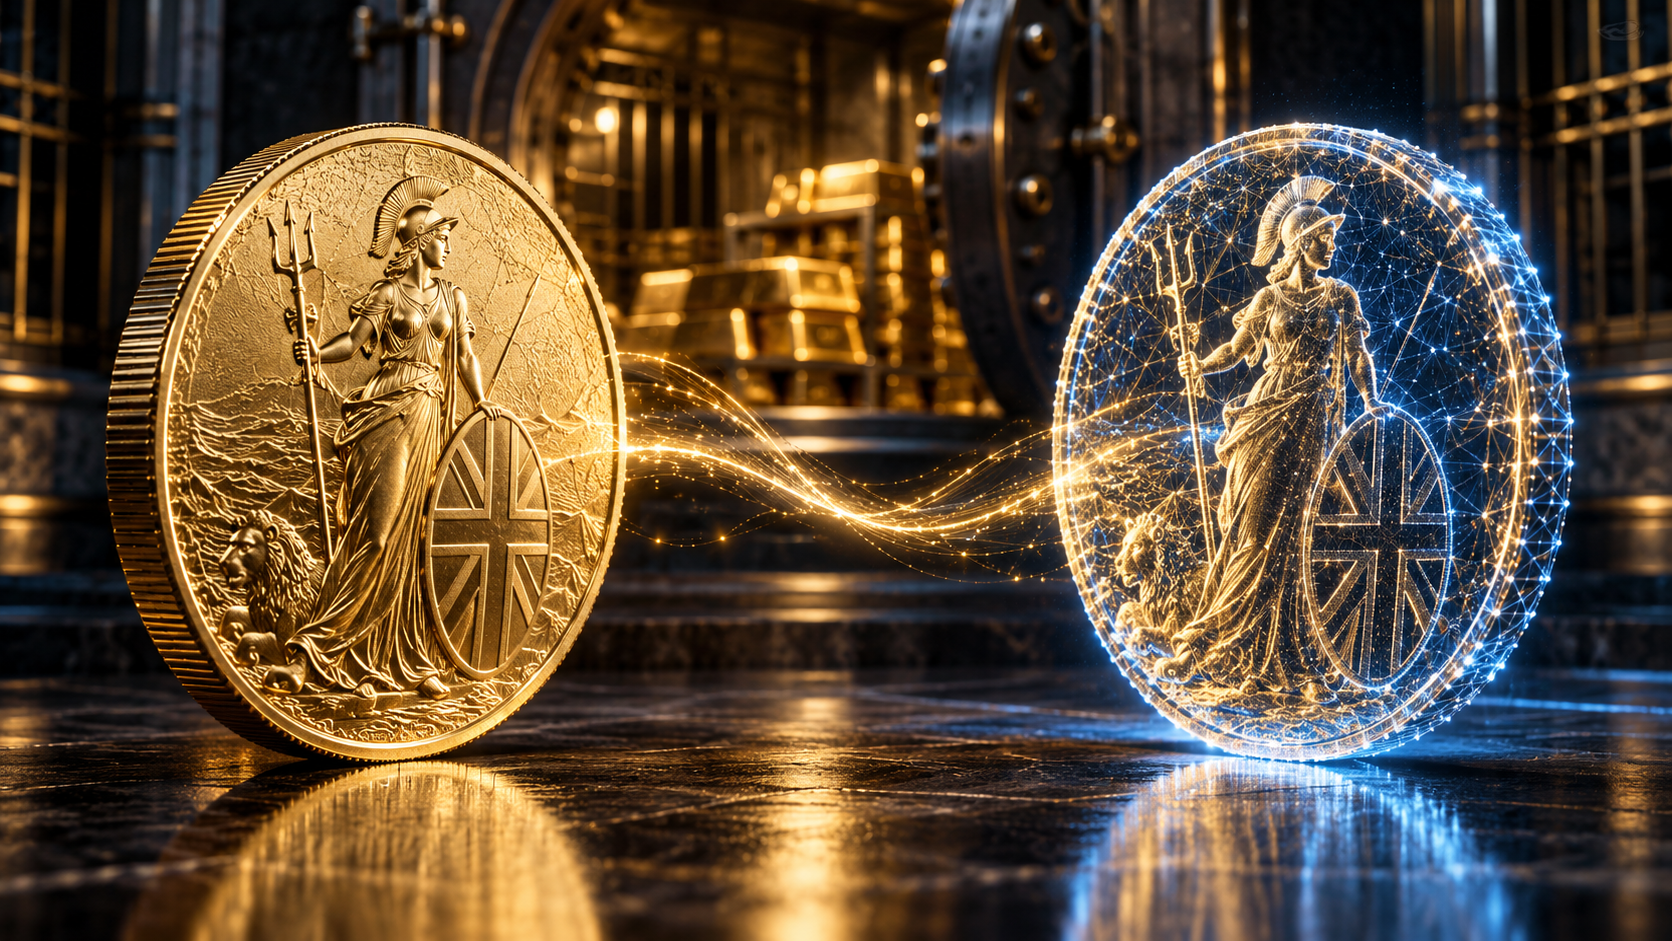
A coin in your hand or a token in your wallet? The next generation may embrace both—but understanding what you own matters more than how you buy it.
By Matthew Jones, Co-founder & Precious Metals Analyst, Britannia Bullion
You can put a gold Sovereign in your hand. Feel its weight. Examine its detail. Give it to your daughter and explain why you bought it.
You can also buy a digital token representing gold held in a vault, then transfer it without moving the metal.
The gold behind those two experiences may be equally real. The ownership arrangements, responsibilities and routes to accessing it can be very different.
As Britain’s regulators explore the future of tokenised gold, that distinction deserves attention.
Because the first question should always be simple:
What, exactly, do I own?
Why this discussion matters now
In September, the Financial Conduct Authority published a call for input on tokenised gold, with responses due by 23 October 2026. It is examining whether tokenisation could improve how gold is traded, transferred, held and used as collateral, particularly in wholesale markets.
Among the issues under consideration is whether certain arrangements could fall within collective investment scheme or alternative investment fund rules, and whether clarification or targeted changes would be appropriate. This is an exploration of policy—not blanket approval of gold tokens.
My view is that the discussion itself is significant. An asset often presented as old-fashioned is being considered for a role in the next generation of financial infrastructure.
The technology is new. The asset giving it credibility is rather older.
What is tokenised gold?
A gold token is a digital record, typically held and transferred on a blockchain, representing an interest in gold stored elsewhere.
In a properly structured arrangement, that interest can include ownership rights in the underlying bullion. It would therefore be misleading to dismiss every token as merely a promise with no real gold behind it.
For example, Paxos states that each PAX Gold token corresponds to one fine troy ounce of allocated gold, held in custody for token holders. Its terms govern ownership, transfers and redemption. That is an illustration of one structure, rather than a recommendation or a description of every product.
The important distinction is between the metal and the machinery surrounding it.
The token records and transfers your interest. The bullion remains in a vault. Your practical position depends on how those two are connected.
Physical possession brings control—and responsibility
When you own genuine bullion outright and take possession, you hold the asset itself.
You do not need an issuer’s app to show that it exists. A platform outage does not make the coin disappear. Holding it does not require a password or a functioning blockchain.
For people buying gold partly to reduce their dependence on financial infrastructure, that independence can be central to the decision.
But physical possession brings responsibilities. Secure storage, suitable insurance and arrangements for inheritance deserve serious thought. Buyers also face premiums above the underlying gold price and a difference between purchase and resale prices. Gold must eventually be sold through a willing buyer; possession does not guarantee instant access to cash.
Professional vaulting is another option. It can provide outright ownership without home storage, although the custody agreement and arrangements for access still matter.
Buying physical gold does not necessarily mean keeping it in your house.
“Backed by gold” is the beginning of the questions
A digital token can make buying and transferring gold more convenient. It cannot, by itself, answer every question about the bullion behind it.
Who holds the metal? How is the backing checked? Does the holder own gold, or have a contractual claim against a business? What happens if the issuer or custodian fails?
And then there is redemption.
Being able to sell a token for money is different from being able to receive physical gold. Minimum quantities, eligibility checks, delivery locations, fees and waiting periods can determine whether physical redemption is practical for an ordinary saver.
The World Gold Council identifies inconsistent redemption arrangements, varying standards of backing and differences in governance as challenges across digital gold products. It also cautions that spreads, platform charges and blockchain fees can materially affect costs. Convenience should be assessed alongside the full price of using it.
A useful question is:
If I wanted the metal, rather than the screen balance, what would happen next?
Digital ownership introduces digital dependencies
Tokenisation can reduce the need to transport bullion whenever ownership changes. However, investors must also understand wallet security, platform access and the powers retained by an issuer.
Holding a token in your own wallet does not necessarily remove those powers. Paxos’s terms, for example, provide for freezing and seizure in specified circumstances, including compliance with legal directives. The significance is that control depends on both the technology and the legal terms.
A digital record can make ownership easier to transfer. It does not make the surrounding institutions irrelevant.
How might the next generation choose?
I can see a plausible future in which a young saver’s first purchase of gold happens through a phone.
They may want to start with a small amount, add regularly and see their holding alongside their other assets. Tokenisation can make fractional ownership easier and connect gold with digital financial services. The World Gold Council sees this development as part of a broader shift supported by younger investors familiar with digital assets.
That could introduce gold to people who would otherwise never consider it.
It does not follow that they will never want a coin or bar.
Someone might begin digitally, accumulate over time and later choose physical possession. Another investor might keep bullion as a long-term reserve while using a digital product for easier transfers.
My expectation is that the next generation will choose according to purpose. Convenience for one part of their finances; direct possession for another.
The industry should help them understand those choices.
The future still needs the metal
There is something revealing about the phrase “gold-backed token”.
For all the sophistication of the technology, the proposition still rests on gold existing somewhere—and on the holder having enforceable rights to it.
Tokenisation may broaden access, improve transfers and create new uses for bullion. Physical possession will continue to appeal to people who value holding an asset directly.
Both deserve an informed discussion.
Before choosing either, ask what you own, who controls access, what it costs and how you leave the arrangement.
The next generation may buy gold differently. They should understand their ownership just as clearly.
About the author
Matthew Jones is Co-founder and Precious Metals Analyst at Britannia Bullion. He writes about gold, economic developments and the role of physical precious metals in protecting, preserving and passing on wealth.
This article provides general information, not personal investment advice. Gold prices can fall as well as rise, and gold produces no income. Costs and legal protections vary by product and provider. Regulatory discussion does not constitute endorsement of an individual product. Regulatory position checked on 21 October 2026.