Oct 7, 2026 · Matthew Jones
AI, energy and debt are putting pressure on the same economic fault lines.
By Matthew Jones, Co-founder & Precious Metals Analyst, Britannia Bullion
7 October 2026
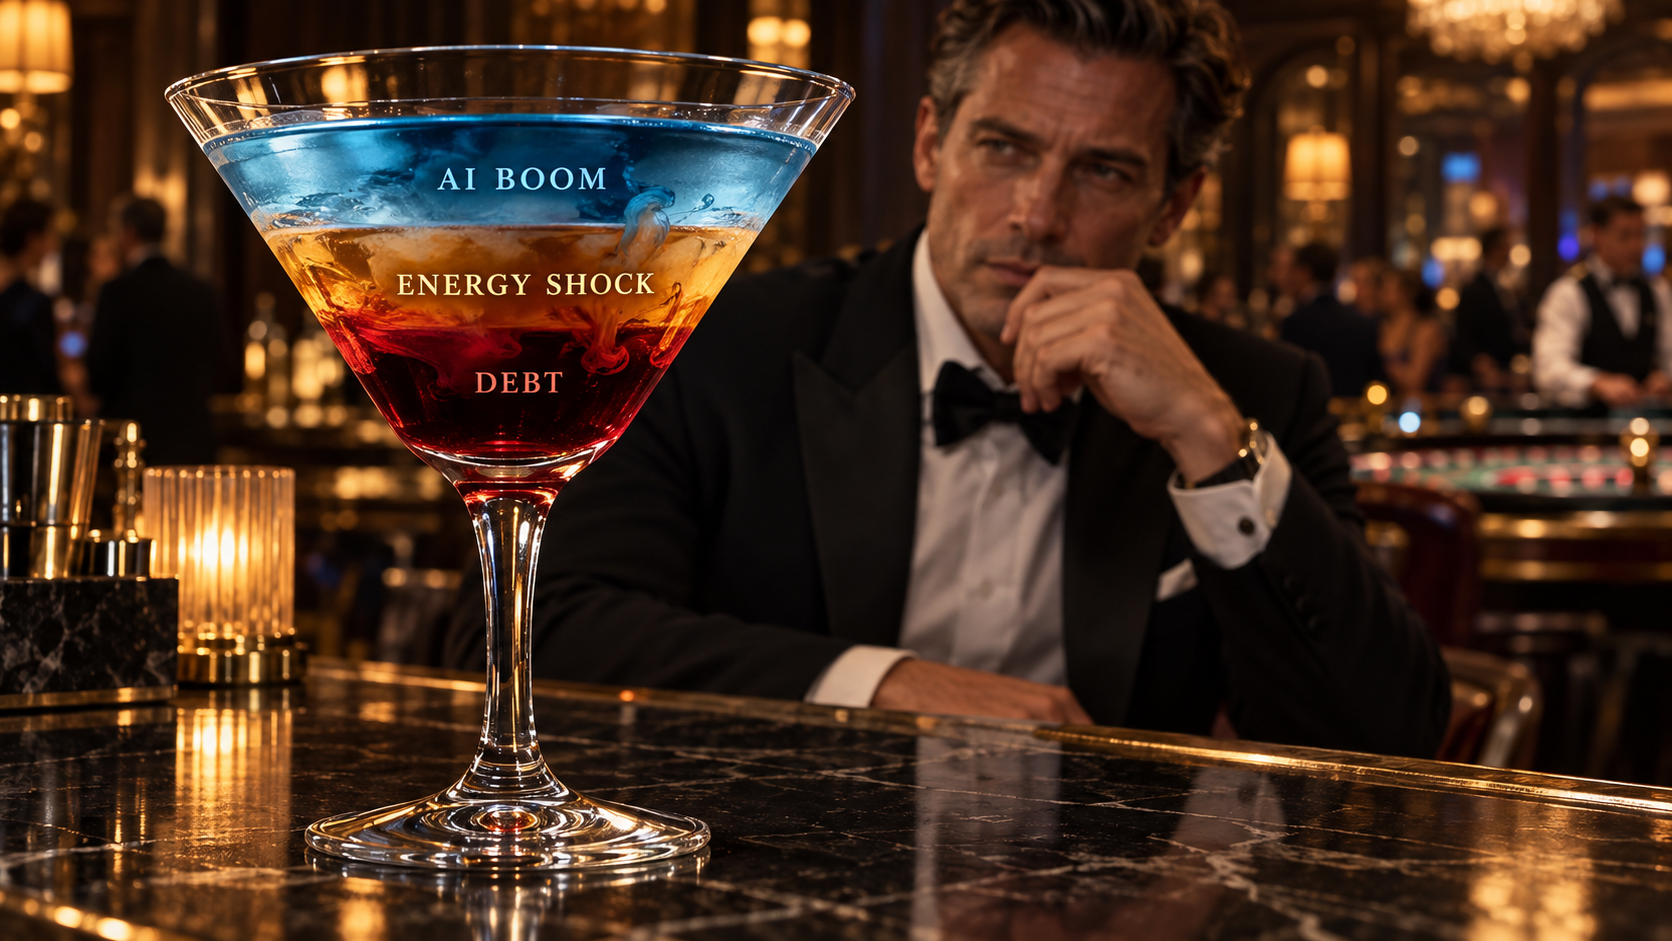
A technological revolution. An energy shock. A mountain of debt.
Each presents a challenge on its own. Together, they create a harder question: what happens when the response to one problem makes another worse?
In remarks reported on 7 October, IMF Managing Director Kristalina Georgieva warned that AI investment, persistent energy pressures and heavy debt burdens are confronting policymakers simultaneously. She urged greater monetary caution and difficult decisions on government finances.[1]
The significance is in the combination. Energy disruption can push prices higher. AI construction adds demand for power and infrastructure. Interest rates intended to contain inflation then increase the cost of servicing debt.
For households trying to preserve what they have built, that interaction deserves attention.
The future needs electricity today
AI is often presented as a route to greater productivity and lower costs. That potential matters. But the infrastructure must be built before its promised benefits can be fully realised.
Data centres, chips, electricity connections and cooling systems require substantial investment. The IMF has identified this spending as a source of near-term demand and inflationary pressure, particularly when energy supplies are already constrained.[2]
There is a timing problem here. The construction bill arrives before the productivity dividend.
There is also a distribution problem. Strong profits for technology companies would not, by themselves, establish that workers, households and public finances were benefiting equally.
If increasingly capable systems reduce demand for human labour, the consequences could extend beyond employment. Weaker earnings could restrain consumer spending, while a smaller wage-tax base could put additional pressure on government finances.
That is a risk scenario, rather than an established outcome. Neither the scale of displacement nor the balance between new opportunities and lost employment is settled. But historical experience with earlier technologies cannot guarantee that general-purpose AI will follow the same path.
AI could eventually relieve some economic pressures. It could also create new ones during the transition.
Energy reaches far beyond the petrol pump
Energy costs work their way through transport, manufacturing, agriculture and household bills.
An extended disruption can therefore squeeze both businesses and consumers. Companies must decide how much of the increase to absorb and how much to pass on. Households have less money available for other spending.
A diplomatic breakthrough would be welcome, but restoring supply chains, damaged infrastructure and depleted reserves can take longer than announcing a ceasefire.
The IMF's September assessment highlighted reserve replenishment and winter demand as continuing vulnerabilities.[3] The implication is that energy pressures can outlast the event that first created them.
Central banks face an awkward choice. Higher rates cannot produce more fuel, but they can restrain spending and help prevent an initial price shock from becoming persistent inflation.
That restraint has a cost of its own.
Debt makes the choices harder
A large debt burden is easier to carry when financing is cheap and incomes are growing. It becomes more demanding when borrowing costs rise.
The adjustment is gradual for debt issued at fixed rates: yesterday's borrowing does not all become more expensive overnight. The pressure builds as debt matures and must be refinanced, alongside any new borrowing.
Consider a simplified example. Refinancing £100 billion at 6% rather than 3% adds £3 billion to annual interest costs on that amount. That is money unavailable for other purposes unless revenue increases or borrowing rises further.
Governments then face competing demands: public services, defence, infrastructure, ageing populations and interest payments.
Higher taxes can weaken private spending. Spending cuts can create economic and political strain. More borrowing can deepen the financing problem.
Inflation may reduce the real value of some existing fixed-rate debt, but it also damages purchasing power and can increase the cost of future borrowing. It offers no painless escape.
When the ingredients reinforce each other
This is the central danger of the cocktail.
Energy pressures can prolong inflation. AI investment can add demand before productivity improves. Higher rates can increase refinancing costs. Fiscal restraint can then weaken growth, making debt harder to manage relative to the economy.
There is a more favourable path. Energy supplies could recover, AI could deliver broad productivity gains, and credible fiscal decisions could rebuild confidence.
There is also a less comfortable possibility: expensive energy, disappointing investment returns and tighter financing arriving together.
These are scenarios, not forecasts. They illustrate why a plan built around rapidly falling rates and uninterrupted asset growth deserves another look.
Where physical gold fits
For wealth preservation, the practical question is how exposed a portfolio is to the same assumptions.
Physical gold has a distinctive characteristic: the metal itself is not a promise by a company or government to repay its owner. That can make it worth considering within a diversified approach.[4]
Ownership still carries practical responsibilities, including secure custody, insurance and the terms of any storage arrangement. Buying premiums and selling spreads also affect the return an owner actually receives.
Gold produces no income, and its price can fall. Higher real yields, a stronger dollar or improving confidence can create headwinds.[4][5] It does not reliably offset every inflation shock or market decline.
The case for considering gold therefore rests on its role within a broader plan, the costs involved and the owner's circumstances—not an assumption that bad news guarantees a higher price.
The IMF's warning gives us reason to examine how risks connect. For anyone protecting wealth intended to support retirement or the next generation, that is a useful place to begin.
A resilient plan needs room for more than one version of the future.
About the author
Matthew Jones is Co-founder & Precious Metals Analyst at Britannia Bullion. He writes on gold, monetary policy and the economic forces shaping wealth preservation, with a focus on the role, risks and practicalities of physical ownership.
This article provides general information, not a personal investment recommendation. Gold prices can fall as well as rise, and past performance does not reliably indicate future results.
Sources
- Reuters, “IMF chief warns energy shock, growing debt and AI risks threaten global growth”, 7 October 2026: https://www.reuters.com/world/
asia-pacific/imf-chief-warns- energy-shock-growing-debt-ai- risks-threaten-global-growth- 2026-10-07/ - IMF, “Europe and the Global AI Race”, September 2026: https://www.imf.org/en/news/
articles/2026/09/20/sp091926- europe-and-global-ai-race - IMF, “Monetary Policy with Supply Shocks and High Debt”, 7 September 2026: https://www.imf.org/en/news/
articles/2026/09/07/sp090726- md-monetary-policy-with- supply-shocks-and-high-debt - World Gold Council, “Potential risks and challenges”: https://www.gold.org/goldhub/
research/relevance-of-gold-as- a-strategic-asset/risks- challenges - World Gold Council, “Gold Mid-Year Outlook 2026: Point break”: https://www.gold.org/goldhub/
research/gold-mid-year- outlook-2026